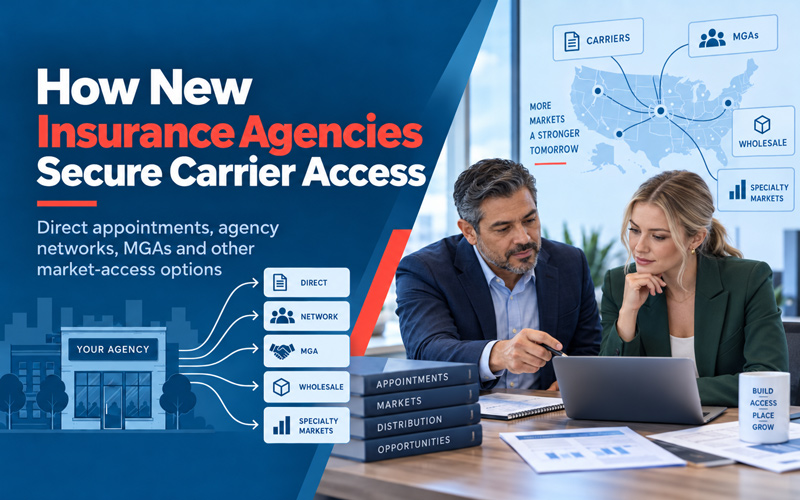
Direct appointments, agency networks, MGAs and other market-access options
Key takeaways
- A target market is only useful if you have a realistic way to place the business you intend to pursue.
- Direct appointments, networks and wholesale relationships solve different access problems, so the right mix depends on your agency model and the clients you plan to serve.
- Book ownership, data rights, termination terms and transferability can affect agency value long after the first appointment is secured.
- Focus on relevant primary and backup markets rather than building the longest possible carrier list.
Why Market Access Should be Planned Before Launch
Client demand alone does not make a niche viable. You also need carriers or intermediaries willing to consider the risks you intend to write. For a startup, market access is therefore part of the business model, not an administrative task to solve after formation.
Your access structure can affect the products you can offer, the territories you can serve, how commissions are earned and how portable the book may be later. NAPA’s broader guide to starting an insurance agency explains where market access fits in the full launch plan. Here, the focus is on choosing and evaluating the access itself.
What Carriers May Evaluate Before Appointing a New Agency
Appointment standards vary by carrier, line and territory. A carrier may look at your experience, licensing, business plan, expected production, target classes, geography and ability to service the business. Current appetite and distribution strategy matter too.
- Relevant production, underwriting or agency experience
- A clearly defined target market and sales plan
- Expected premium volume and product mix
- Territory, catastrophe exposure and class mix
- Submission quality and servicing capacity
No single factor guarantees an appointment. A clear business plan can help a carrier understand where you fit, but the carrier still controls its underwriting and distribution decisions. If you are still deciding between business models, NAPA’s guide to captive vs. independent insurance agents explains how independence changes carrier access, business control and operating responsibility.
Compare the Main Market-Access Options
Direct carrier appointments
A direct appointment creates a relationship between your agency and the carrier without routing production through a network or another retail intermediary. For the right agency, that can mean clearer carrier visibility and more control over the relationship, with economics that may improve as production grows.
The challenge is access. Many carriers look for established experience, meaningful production or a specific territorial need. A new agency may not meet those expectations immediately, and taking on aggressive production commitments too early can leave too much of the book dependent on one market.
Direct does not mean unrestricted. The appointment agreement may still address production, termination, commission rights, data use and post-termination servicing.
Agency networks, clusters and aggregators
Networks, clusters and aggregators can help new agencies reach markets they may not be able to access directly. Depending on the model, they may also offer placement support, training, technology or shared services. Some place business through the network while others help member agencies establish direct appointments.
Do not judge the relationship by carrier count alone. Look at whether the available markets fit the business you intend to write and understand how fees, commission splits, data rights and exit terms affect the agency if the relationship changes. Fees, commission splits and production requirements should also be reflected in your insurance agency startup costs and operating plan.
MGAs, wholesalers and E&S brokers
MGAs, wholesalers and E&S brokers can open access to specialty, emerging or difficult-to-place risks that do not fit standard appointments. These relationships can be especially important for catastrophe-exposed property, unusual commercial classes or accounts with more complex underwriting needs.
Know who has underwriting or binding authority, which insurer ultimately writes the risk and what the submission requires. Clean, complete exposure information can make the placement process more efficient and reduce avoidable back-and-forth.
Build a Market-Access Map Before Launch
A market-access map connects each intended client segment to a realistic primary and backup placement path. The point is not to create another carrier list. It is to see where the business plan depends on access that is uncertain, narrow or concentrated.
|
Target business |
Primary path |
Backup path |
Restriction to confirm |
|
Preferred personal lines households |
Direct carrier or network market |
Second carrier or network option |
Territory, bundling and catastrophe appetite |
|
Small commercial accounts |
Direct small-commercial market |
MGA or wholesaler |
Class, revenue and property limits |
|
Specialty commercial risks |
MGA or wholesale market |
Alternative wholesaler |
Submission requirements and authority |
|
Life and health clients |
Carrier or general-agency relationship |
Additional carrier relationship |
Appointment, eligibility and compensation rules |
Update the map as carrier strategies change. If an important segment has no credible backup path, treat that as a business risk rather than assuming another market will appear when you need it.
Review Market-Access Contracts as Long-Term Asset Documents
Market-access agreements can influence the agency’s economics and value years after launch. Do not assume that client records, appointments, commissions or servicing rights automatically follow the agency if the relationship ends. These questions can be especially important for producers transitioning from captive to independent, where existing agreements may also affect client relationships, solicitation and future carrier access.
|
Question to resolve |
Why it matters |
|
Who owns the book and expirations? |
Ownership can affect servicing rights, transferability and agency value. |
|
Are appointments direct or through the network? |
The carrier relationship may change after the agency leaves. |
|
How are commissions and fees handled? |
Splits, deductions and contingent-income rules affect account economics. |
|
What happens at termination? |
Exit provisions may govern data, policies, renewals and future access. |
|
Can the agency export complete data? |
Operational independence depends on usable client and policy records. |
|
Can the book be sold or assigned? |
Transfer provisions affect succession planning and valuation. |
Qualified legal and financial professionals should review material agreements. The questions below are intended to help you identify what needs to be understood before you commit, not to replace legal advice.
Avoid Excessive Carrier and Access Concentration
Concentration often develops because one carrier has attractive pricing, broad appetite or an easier appointment path. That can feel efficient until a carrier changes appetite, tightens underwriting, reduces capacity or ends the appointment and a large portion of the book is affected at once.
Track premium and revenue by carrier, intermediary, line and geography. Diversify when client need or concentration justifies it, not simply to collect appointments. Every additional market also creates training, portal, submission and renewal requirements for the agency.
How Market Access Should Evolve During the First Three Years
The goal is not maximum access. It is enough durable, relevant access to serve the market you chose without creating unnecessary operational complexity.
|
Phase |
Primary objective |
What to do |
|
Launch |
Serve the chosen niche |
Use enough viable markets to handle common risks plus a practical backup path. |
|
Development |
Strengthen relationships |
Use consistent production, clean submissions and service quality to improve access and pursue direct appointments selectively. |
|
Diversification |
Reduce dependency |
Add markets based on client need, concentration and operating capacity rather than prestige. |
Connect Market Access to the Full Launch Plan
Market access should be evaluated alongside your niche, startup budget and service capacity. Review How to Start an Insurance Agency in 2027 for the complete launch roadmap and Insurance Agency Startup Costs and Systems for the financial and operational effects of access fees, commission splits and added market complexity.
If a carrier, network or other market partner requires E&O insurance, confirm that your agency’s arrangement satisfies the requirement and aligns with the services you plan to provide. NAPA supports independent agents and agencies with practical risk-management resources and specialized E&O options.
è Explore agency E&O options or schedule a complimentary insurance consultation
Read Part 1: How to Start an Insurance Agency in 2027
Read Part 3: Insurance Agency Startup Costs and Systems
Frequently Asked Questions
How many carrier appointments does a new agency need?
There is no universal number. A startup needs enough relevant primary and backup options to serve its target clients without creating avoidable complexity. Relevance matters more than appointment count.
Can a startup agency obtain direct carrier appointments?
Sometimes. Availability depends on the carrier’s strategy, territory, product, experience requirements and expected volume. A network, MGA or wholesaler may provide another path when direct access is not available.
Does joining an aggregator mean the agency owns its book?
Not necessarily. Book ownership, data rights and post-termination servicing depend on the specific agreement and related carrier contracts. Confirm those rights before assuming the book is fully portable.
Can an agency leave a network and keep its clients?
It depends on book ownership, carrier appointments, data access and termination provisions. Understand those terms before joining and obtain legal review when the rights are material to agency value.
After centuries of cautious management, insurance faces a tech wave threatening the role of human agents. But will AI reshape the industry as expected? Find out in our free whitepaper.